Fixed vs Variable Small Business Loan Rates: Which Is Right for You?
By Laurel C. Yazzie | Last reviewed: September 2026
When you apply for a small business loan, one of the first decisions the lender will ask you to make is whether you want a fixed or variable interest rate. That choice affects every payment you make for the life of the loan, and it shapes your cash flow in ways that go far beyond the number on your approval letter.
In reviewing hundreds of loan applications over a decade in consumer lending, the detail most borrowers miss is that the rate type they choose at closing is almost always harder to change than the rate itself. Refinancing out of a variable rate mid-term is not guaranteed, and the conditions that make you want to refinance are often the same ones that make it harder to qualify.
This guide compares fixed vs variable small business loan rates side by side, shows which loan products typically use each structure, and gives you a concrete decision framework so you can choose with confidence before you sign.
What Fixed vs Variable Small Business Loan Rates Actually Mean
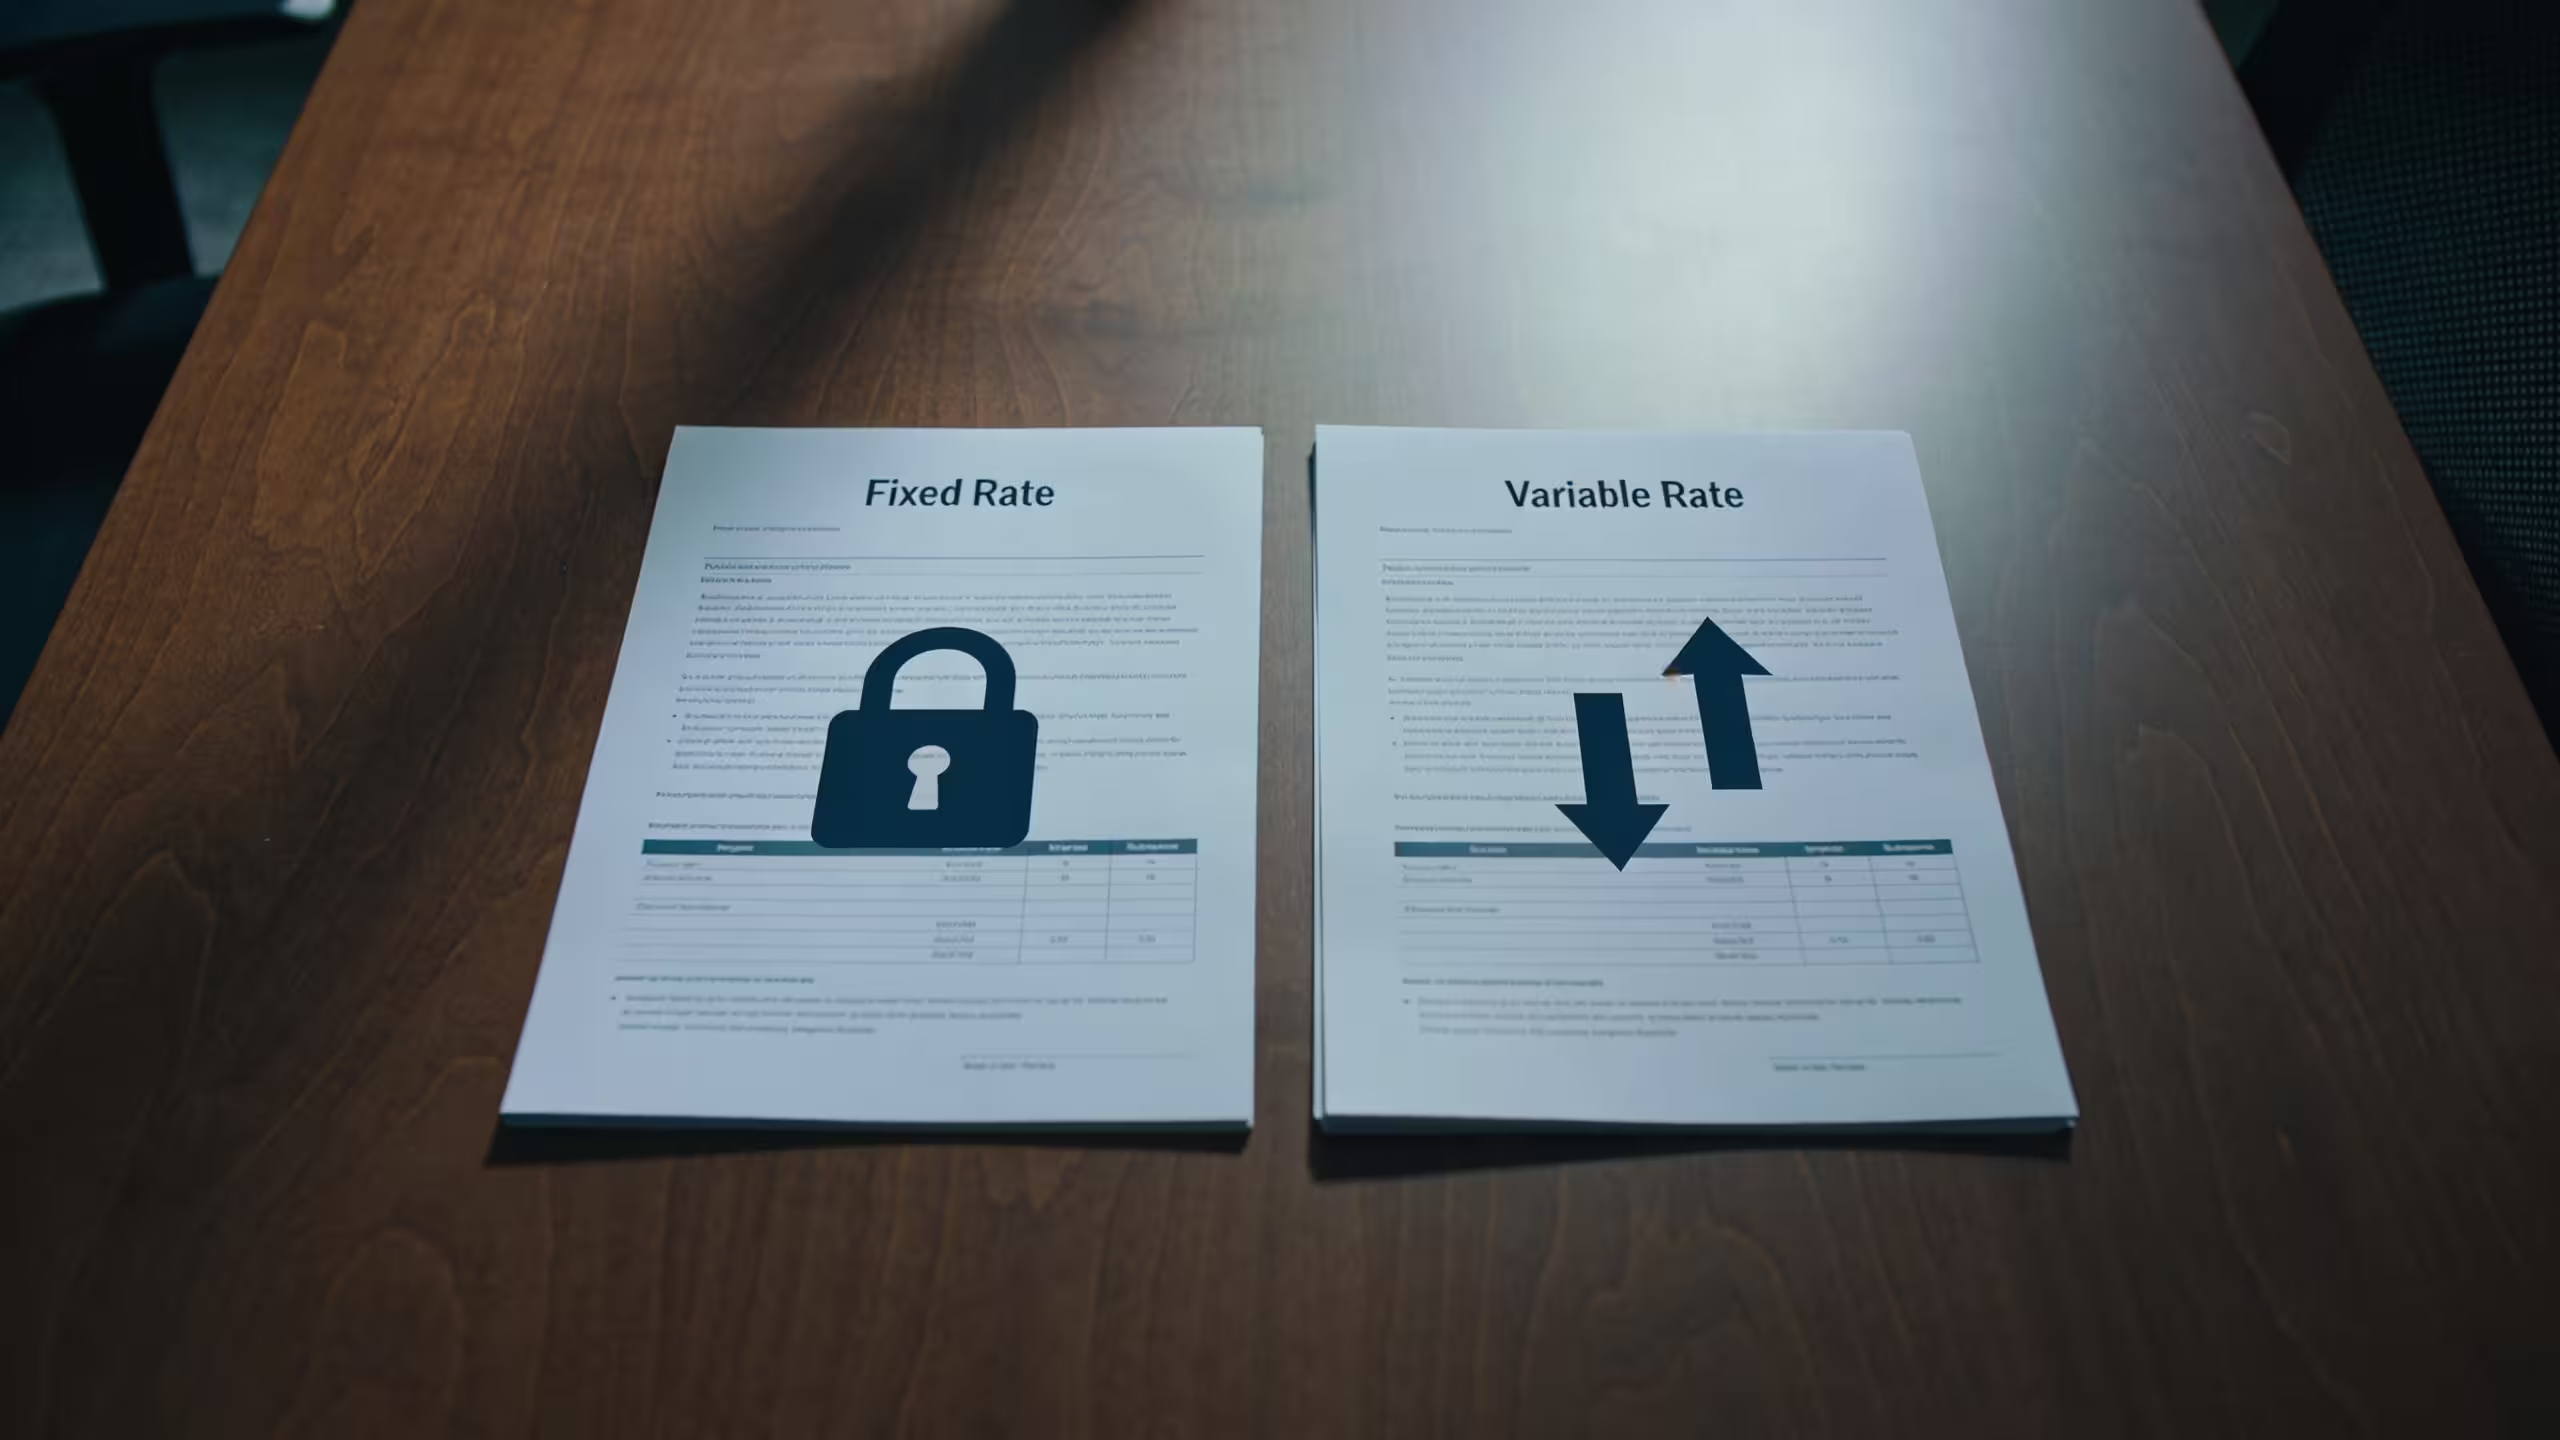
A fixed interest rate is locked at closing and does not change for the entire repayment term. Whether rates across the economy rise or fall after you borrow, your monthly payment stays the same.
A variable interest rate is tied to a benchmark, typically the U.S. prime rate, and adjusts periodically as that benchmark moves. When the prime rate rises, your rate and monthly payment rise with it. When the prime rate falls, your costs drop too. According to the Federal Reserve, banks use the federal funds rate as the foundation for setting their own lending rates, and the prime rate that most variable business loans reference moves in step with it.
| Feature | Fixed Rate | Variable Rate |
|---|---|---|
| Monthly payment | Stays the same throughout the term | Can rise or fall as the benchmark moves |
| Starting rate | Often set slightly higher than variable at origination | Often starts lower than a comparable fixed rate |
| Rate risk after closing | None: your rate is locked regardless of market moves | Payments can increase if the benchmark rises |
| Budgeting ease | Simple: exact payment is known from day one | Requires planning for multiple rate scenarios |
| Best rate environment | Rising or uncertain rate environment | Falling or stable rate environment |
| Total loan cost | Known at closing | Not known until the final payment is made |
Which Business Loan Types Are Fixed or Variable by Default?
Not every loan product gives you an equal choice between rate structures. Some products default to one type, and knowing this narrows your decision before you compare a single lender quote.
| Loan Type | Typical Rate Structure | Notes |
|---|---|---|
| SBA 7(a) loan | Variable (fixed also available) | Both structures are permitted, subject to SBA rate maximums pegged to the prime rate |
| SBA 504 loan | Fixed (CDC portion) | The certified development company portion of 504 loans is typically fixed, providing long-term rate certainty for real estate and equipment |
| Business term loan | Often fixed | Especially common for longer terms; varies by lender |
| Business line of credit | Usually variable | Rate adjusts as draws are made and market conditions change |
| Working capital loan | Variable or short-term fixed | Short repayment windows reduce rate exposure under either structure |
| Equipment financing | Often fixed | Lenders typically align the rate structure to the useful life of the asset being financed |
According to the U.S. Small Business Administration, interest rates on 7(a) loans are negotiated between the borrower and the lender and may be fixed or variable, but are subject to SBA maximums pegged to the prime rate. For variable rate 7(a) loans, the SBA notes that the lender may require a different payment amount each time the interest rate changes.
Fixed vs Variable Rates: Pros and Cons
What most people miss when comparing loan offers is that the starting rate is only one data point. Over a five- or seven-year repayment term, how the rate structure behaves through changing market conditions matters more than where the rate begins.
| Fixed Rate Loan | Variable Rate Loan | |
|---|---|---|
| Pros |
|
|
| Cons |
|
|
| Best for | Long-term loans, businesses with tight or seasonal revenue, borrowers who prioritize cash flow stability over rate optimization | Short-term financing, businesses with strong cash reserves, borrowers confident the rate environment will remain stable or decline during repayment |
How to Choose Between Fixed vs Variable Small Business Loan Rates
From a practical standpoint, the choice between these two structures comes down to two questions: How predictable is your monthly revenue, and how long is your loan term? Use this framework to reach a decision before you compare lenders.
- If your loan term is longer than five years and a payment increase would force you to cut staff or reduce inventory, choose fixed. The rate certainty is worth the slightly higher starting point.
- If your loan term is under three years and you have enough cash reserve to absorb a rate increase, variable may lower your total cost, particularly if the broader rate environment is flat or declining.
- If your revenue is seasonal or irregular, fixed is the safer choice. A variable rate can rise precisely when your cash flow is already under seasonal pressure, compounding the stress.
- If you are using an SBA 504 loan for real estate or major equipment, the rate structure decision is made for you: the CDC portion of a 504 loan is typically fixed, providing long-term payment certainty from closing.
- If you are drawing on a business line of credit, plan for a variable rate from the start. Expect the rate to move, and build your draw decisions around that assumption.
- If you are early-stage with limited operating history, fixed rates reduce uncertainty during the period when your revenue is least predictable and your financial cushion is thinnest.
What Happens If Rates Spike on a Variable Loan Mid-Term?
This is the scenario most borrowers do not think through before signing. If you carry a variable rate business loan and market rates rise significantly during your repayment term, your monthly payment increases. That increase is not connected to your business performance or revenue. It follows the benchmark regardless of how your business is doing.
In practice, many borrowers in this situation look to refinance into a fixed rate loan. But refinancing is not guaranteed. To qualify, your business typically needs to meet the lender’s current underwriting standards, which may be stricter than when you first borrowed. If your revenue has softened, or if credit conditions have tightened in the same environment that pushed rates up, you may not qualify for a fixed-rate refinance at the moment you need it most.
The practical implication is this: if there is any realistic chance you cannot absorb payment increases over your full loan term, do not rely on refinancing as a fallback. Choose the rate structure you can live with from closing day forward, not the one that only works if the best-case scenario holds.
How Rate Type Connects to Loan Type: The Next Question Most Borrowers Ask
After deciding between rate structures, many borrowers want to understand how the overall loan product compares to other options: specifically whether a term loan or a line of credit better fits how their business actually uses capital. That product decision interacts directly with the rate structure available to you. Our guide on term loans vs lines of credit covers how each product works and which type of business need each serves best.
The Rate Is Only Part of What You Are Paying
Whether your rate is fixed or variable, comparing loans by interest rate alone gives you an incomplete picture of cost. The annual percentage rate (APR) includes the interest rate plus fees folded into the loan over the repayment period, such as origination fees and, for SBA loans, the guarantee fee the lender passes to the borrower. Two loans with the same stated interest rate can have meaningfully different APRs when fees are factored in.
- Always ask the lender for the APR, not just the interest rate, before comparing offers side by side.
- For variable rate loans, ask whether there is a rate cap, and how frequently the rate can adjust during the term.
- For SBA loans, confirm whether guarantee fees are rolled into the loan balance or paid upfront at closing, as this affects the true cost of borrowing from day one.
For a deeper look at the six factors that determine the rate you are offered before the fixed vs variable decision even comes into play, see our guide on factors that affect business loan rates. For a complete overview of every guide in this cluster, visit our small business loan guides.
FAQ: Fixed vs Variable Small Business Loan Rates
Tap any question to expand the answer.
What is the main difference between a fixed and variable rate business loan?
A fixed rate stays the same for the entire repayment term, so your monthly payment never changes regardless of what happens in the broader economy. A variable rate is tied to a benchmark, usually the U.S. prime rate, and adjusts periodically as that benchmark moves up or down. Fixed rates provide payment certainty; variable rates introduce the possibility of lower costs if rates fall, but also the risk of higher costs if they rise. The right structure depends on your loan term, your revenue predictability, and how much payment variability your cash flow can absorb.
Are SBA loans fixed or variable rate?
It depends on the SBA program. According to the U.S. Small Business Administration, 7(a) loan rates may be fixed or variable, and are negotiated between the borrower and the lender subject to SBA rate maximums pegged to the prime rate. SBA 504 loans, used primarily for commercial real estate and major equipment purchases, typically carry a fixed rate on the CDC portion of the loan, providing long-term payment certainty. Because SBA variable rates are subject to government-set ceilings, even a variable SBA 7(a) loan has a cap on how high the rate can climb, which distinguishes it from conventional variable rate loans with no such ceiling.
Can I switch from a variable to a fixed rate after I take out a business loan?
Switching from variable to fixed typically requires refinancing, which means applying for a new loan to pay off the existing one. Refinancing is not guaranteed: your business must meet the lender’s current underwriting standards at the time you apply, which may differ from the standards in place when you originally borrowed. The period when you most want to switch, when market rates are rising and payments are increasing, is often the same period when lenders are tightening credit and refinancing is harder to qualify for. For this reason, it is worth choosing the rate structure you can sustain for the full loan term rather than relying on a future refinance as an exit option.
Which rate type is better for a small business with seasonal revenue?
For businesses with seasonal or irregular revenue, a fixed rate is generally the safer choice. A variable rate can rise during a period when your cash flow is already under seasonal pressure, creating a situation where your highest payments coincide with your lowest revenue. A fixed rate keeps your loan obligation the same month to month, which makes it easier to plan around your revenue cycles without adding payment variability on top of income variability. Businesses with consistent, predictable monthly revenue have more flexibility to absorb variable rate changes.
Does the Federal Reserve’s rate affect my existing business loan?
Only if your loan has a variable rate. When the Federal Reserve raises or lowers the federal funds rate, banks adjust their prime rate accordingly, and variable rate business loans tied to the prime rate adjust with it. If you have a fixed rate loan, changes in the Federal Reserve’s rate decisions have no effect on your existing loan payment, because your rate was locked at closing. This is one reason borrowers who take out fixed rate loans in a rising rate environment end up paying less over time than those who chose variable at the same moment. Your rate type at origination is what determines your exposure to future Fed decisions.