Same Day Small Business Loans: How to Get Funded Today
By Laurel C. Yazzie | Last reviewed: October 2026
When a piece of equipment breaks, an urgent supplier invoice arrives, or a short-term opportunity demands immediate capital, waiting three to six weeks for a traditional bank loan is not a realistic option. Same day small business loans exist specifically for moments like these, offering a path from application to funded account in hours rather than weeks.
Same Day Small Business Loans: These are business financing products offered primarily by online alternative lenders that allow eligible businesses to apply, receive approval, and access funds within the same business day. Most require only basic documentation such as bank statements and a completed online application, with underwriting handled by automated systems rather than manual bank review.
In reviewing hundreds of loan applications over a decade in consumer lending, the detail most borrowers miss is the difference between same-day approval and same-day funding — they are not the same thing, and confusing the two is how businesses end up short on a critical deadline.
What Are Same Day Small Business Loans?
Same day small business loans are short-term business financing products designed to move from application to funded bank account within one business day. They are offered almost exclusively by online alternative lenders, not traditional banks. While traditional institutions rely on manual underwriting, document review committees, and multi-step approval chains, online lenders use automated systems that evaluate revenue data, cash flow patterns, and basic business information in minutes.
The table below shows the core differences between same-day and traditional business loan funding:
| Feature | Same-Day Lenders | Traditional Banks |
|---|---|---|
| Time to funding | Hours to 1 business day | 2 to 8 weeks |
| Underwriting method | Automated (bank data, revenue analysis) | Manual review + committee |
| Documentation required | 3–6 months bank statements, basic business info | Tax returns, financial statements, business plan |
| Credit score flexibility | More flexible than traditional banks, thresholds vary by lender | Typically 680+ preferred |
| Cost | Higher rates to reflect speed and risk | Lower rates, more rigorous qualification |
According to the U.S. Small Business Administration, small businesses often face significant hurdles accessing capital quickly through conventional channels, which is why alternative lenders have grown into a major segment of the small business funding market.
Types of Same Day Small Business Loans
Not every product that carries the “same day” label works the same way. Speed varies by loan type, and the fastest products often carry the highest costs. Understanding what is available helps you match the right product to your situation.
| Loan Type | Typical Time to Funds | Best For |
|---|---|---|
| Merchant Cash Advance (MCA) | Same day to 24 hours | Businesses with high card sales volume |
| Working Capital Loan | Same day to 24 hours | Covering immediate operational costs |
| Short-Term Online Term Loan | Same day to next business day | One-time lump-sum expenses |
| Business Line of Credit | 1–3 days to set up; same day to draw after | Recurring short-term cash flow gaps |
| Invoice Financing | Same day to 24 hours | B2B businesses with outstanding invoices |
For a deeper look at what working capital loans cover and how they differ from term products, that guide walks through the structures side by side.
Which Type Is Fastest?
Need funds within a few hours today? A merchant cash advance or working capital loan from an online lender is your most direct path, provided your business generates consistent revenue. Need ongoing access without reapplying? A pre-established business line of credit lets you draw funds the same day after the initial setup is complete.
How Same Day Business Loan Approval Works
The speed of online lending comes from automation. Instead of a loan officer manually reviewing your financials, algorithms analyze your bank account data, revenue trends, and repayment patterns within minutes. Here is the typical sequence for a same day small business loan:
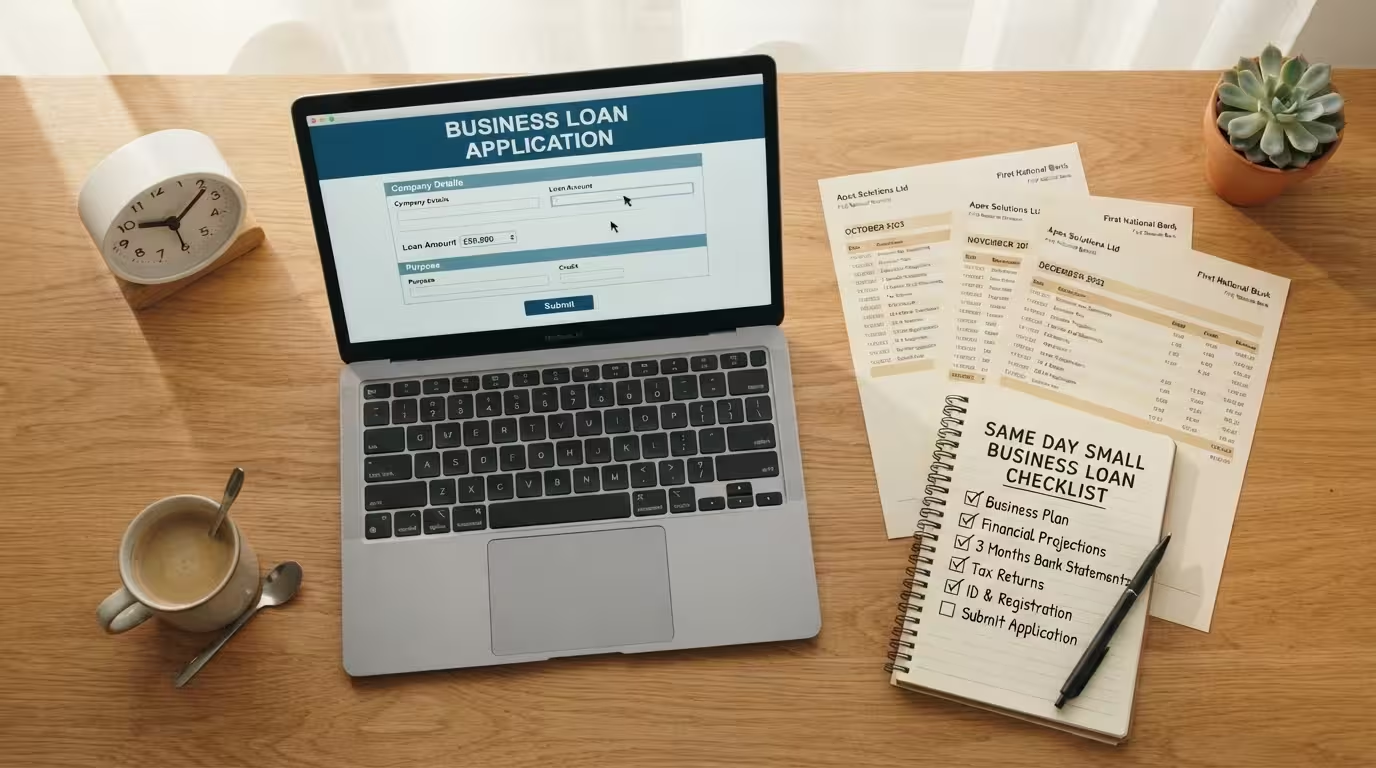
- Submit the online application. Most platforms require basic business information and three to six months of bank statements. Many accept a direct bank data connection, which speeds up the review further.
- Automated underwriting review. The lender’s system assesses cash flow consistency, revenue level, and basic creditworthiness. This step can take minutes to a few hours.
- Receive and review your offer. If approved, you will see the loan amount, repayment structure, and total cost. Review these carefully before signing.
- Sign electronically. The contract is executed digitally. This is the step where timing becomes critical (see below).
- Funds deposited via ACH or wire transfer. ACH takes a few hours and is free on most platforms. Wire transfer is faster but may carry a small fee.
In practice, many borrowers find the application itself takes under 15 minutes. The variable is how quickly the lender’s system processes the bank data and issues a decision.
The Cut-Off Time Rule Most Borrowers Miss
This is the detail most same-day funding guides skip entirely. Receiving funds the same calendar day you apply depends not just on the lender, but on when you submit and sign.
ACH transfers, which most online lenders use, follow Federal Reserve processing windows. Same-day ACH credits must be submitted to the Federal Reserve by specific cut-off times, and the Fed’s Fedwire and FedACH systems have processing windows throughout the business day. Many lenders impose their own internal deadlines: for example, applications signed after 10:30 a.m. local time may not qualify for same-day deposit even if the lender advertises same-day funding.
A borrower who submits a complete application at 2 p.m. may be approved the same afternoon and still not receive funds until the following morning. This is not a bait-and-switch; it is an ACH timing reality. If you genuinely need funds by end of day, submit your application as early in the morning as possible and ask the lender explicitly: “What is your cut-off time for same-day deposit today?”
What You Need to Qualify
Qualification standards for same day small business loans are more flexible than traditional bank products, but lenders do have requirements. Most programs consider the following factors:
- Time in business: Most online lenders require at least six to twelve months of operating history. Some working capital programs work with businesses as young as three months.
- Monthly or annual revenue: Lenders use revenue to assess repayment capacity. Minimum thresholds vary widely by lender and loan type.
- Credit score: Many same-day lenders accept business owners with scores starting around 500 to 600. Lenders set their own thresholds and rarely publish them publicly. Checking your rate through a soft inquiry will not affect your score.
- Bank statements: Typically three to six months of business bank statements are required. The lender reviews cash flow patterns rather than a formal profit-and-loss statement.
- Active business bank account: Funds are deposited directly, so an active business checking account is required.
The Consumer Financial Protection Bureau advises borrowers to review all loan terms carefully before signing, particularly the total repayment amount and any prepayment conditions. For a full overview of the standard factors lenders evaluate, see our guide on how long business loan approval takes across different loan types.
Is a Same Day Small Business Loan Worth the Cost?
Speed comes at a price. Because online lenders take on faster risk decisions and serve borrowers who may not qualify for traditional bank products, their rates are typically higher than bank loans or SBA products. This is the “speed premium” built into same-day financing.
Before applying, use this framework to decide whether same-day funding makes financial sense for your situation:
If the cost of not having the funds today (a missed contract, a broken piece of equipment that halts production, a supplier penalty for late payment) is greater than the total extra interest cost of the fast loan versus a standard loan, same-day financing is the rational choice.
If the need is not time-critical and a few extra business days would not change the outcome, a slower product with lower rates will almost always save money.
When It Makes Sense
Same day small business loans are best suited to genuine urgency: an equipment failure that stops revenue, a time-sensitive bulk purchase at a discount, bridging a payroll gap while a large receivable clears, or covering an unexpected tax obligation. They are not a substitute for long-term capital planning. The Small Business Administration offers longer-term, lower-cost loan programs for businesses with non-urgent capital needs, though those programs typically take weeks to fund.
For a broader look at all your financing paths, see our guide to small business loan options across every major product type.
How to Apply for a Same Day Small Business Loan
Preparation is the single biggest factor in whether you receive funds the same day. Borrowers who have documents ready and submit early in the morning have the highest success rate.
- Gather your documents before you start. Have three to six months of bank statements, your business EIN, and basic revenue figures ready. Some lenders accept a direct bank login to pull statements automatically.
- Check your eligibility before applying. Many lenders offer a soft-pull pre-qualification that does not affect your credit score. Use this to confirm you meet the basic requirements before submitting a full application.
- Compare multiple lenders. Rates, fees, and repayment structures differ. Look at the total repayment amount, not just the advertised rate.
- Submit before the morning cut-off. As discussed above, submitting before mid-morning gives you the best chance of same-day ACH deposit.
- Sign the contract promptly. Once you receive an offer, review it carefully but do not delay. The clock on same-day funding starts when you sign, not when you apply.
FAQ: Same Day Small Business Loans
Tap any question to expand the answer.
Can I really get a business loan funded the same day I apply?
Yes, same-day funding is possible with online alternative lenders, but it depends on two conditions: you must submit and sign your application before the lender’s daily cut-off time (often mid-morning), and your bank must accept same-day ACH credits. If you apply late in the afternoon, funds will typically arrive the following business day. Confirm the cut-off time directly with the lender before you apply if same-day deposit is critical.
What credit score do I need for a same day small business loan?
Lenders set their own credit score thresholds and rarely publish them publicly. Many online lenders that offer same-day funding work with business owners who have personal credit scores starting around 500 to 600, which is lower than most traditional banks require. The most important factor for many same-day lenders is consistent business revenue, not credit score alone. Use a soft-pull pre-qualification tool to check your eligibility without affecting your score.
Are same day business loans more expensive than regular business loans?
Yes, in almost every case. Same-day lenders charge a premium for speed and for the higher risk they take on by approving applications quickly without full manual underwriting. Rates and fees are typically higher than what you would pay through a bank or an SBA loan program. Before signing, calculate the total repayment amount across the full loan term and compare it to the cost of not having the funds immediately. If the urgency is real, the premium is often justified; if it is not, a slower and cheaper loan product will save money.
Do SBA loans offer same-day funding?
No. Standard SBA loan programs, including the 7(a) and 504 loan programs, typically take several weeks from application to funding due to their documentation requirements and multi-step approval process. The SBA Express program moves faster, with a 36-hour approval target, but funding still takes additional time after approval. If you need capital within the same business day, SBA products are not designed for that timeline. The SBA is better suited for longer-term capital needs where lower interest rates and extended repayment terms are the priority.
What is the difference between a merchant cash advance and a same day business loan?
A merchant cash advance (MCA) is technically not a loan. It is an advance against your future revenue, repaid as a percentage of daily card sales or bank deposits. A same-day business loan is a structured debt product with a defined repayment schedule. Both can fund within the same business day, but they have very different cost structures: MCAs use a factor rate rather than an annual percentage rate, which makes comparing their true cost to a loan difficult without converting the figures. Always ask a lender to state the total repayment amount in dollar terms so you can compare accurately.