Fast Approval Student Loans: What to Expect and How to Move Quickly
By Laurel C. Yazzie | Last reviewed: October 2026
If you need student loan funding before your semester starts, timing matters more than most borrowers realize. The phrase “fast approval” suggests money is on the way quickly. In reality, approval is only one of several steps before funds reach your school, and knowing which steps take the longest gives you the best chance of getting funded on time.
Fast Approval Student Loans: Fast approval student loans are primarily private loans that issue a credit decision within minutes to a few days. However, lender approval is only the first step. Before funds are disbursed, your school must certify the loan, a process that adds time regardless of how quickly the lender approves your application.
What Does “Fast Approval” Mean for Student Loans?
The term “fast approval” applies almost entirely to private student loans. Federal loans require a FAFSA submission reviewed by your school, a process that takes weeks and cannot be shortened. Private lenders run their own credit review and can issue decisions much faster.
But a faster lender decision does not equal faster money. Three stages separate your application from funded tuition:
- Lender approval: The private lender reviews your credit and issues a decision
- School certification: The lender contacts your school to confirm enrollment and verify the loan amount; the school must respond before any funds move
- Disbursement: Funds are transferred to your school and applied to your balance
Having worked directly with clients on loan applications for time-sensitive enrollment situations, the most common mistake I saw was applying for a private loan only after federal aid fell short, with just days to spare before tuition was due. By that point, the school certification window alone could push disbursement past the payment deadline.
Why Federal Loans Are Slower (But Still Come First)
Federal student loans require completing the Free Application for Federal Student Aid (FAFSA). According to Federal Student Aid, online FAFSA submissions are typically processed within one to three days. From there, your school uses the data to build your financial aid package, which can take several additional weeks depending on the institution and time of year.
Here is what the federal loan process looks like from start to finish:
| Step | Approximate Wait |
|---|---|
| Submit FAFSA online | 1–3 days for processing (per Federal Student Aid) |
| School reviews data and builds aid package | Several days to several weeks |
| Accept loan offer, complete entrance counseling, sign MPN | Completed on your timeline — required before any disbursement |
| Disbursement | Typically at or just before the term start date |
Federal loans carry lower fixed rates and access to income-driven repayment plans that private loans do not offer. The Consumer Financial Protection Bureau recommends exhausting federal loan options before turning to private lenders. For a full breakdown of both loan types beyond timing, see our guide on how federal and private loans compare.
Fast Approval Student Loans: How Private Lenders Work
Private student loan lenders set their own approval standards and can issue a credit decision faster than any federal program. Some lenders offer online applications that return a decision within minutes of submission. Even so, the speed of the lender’s decision is only part of the story.
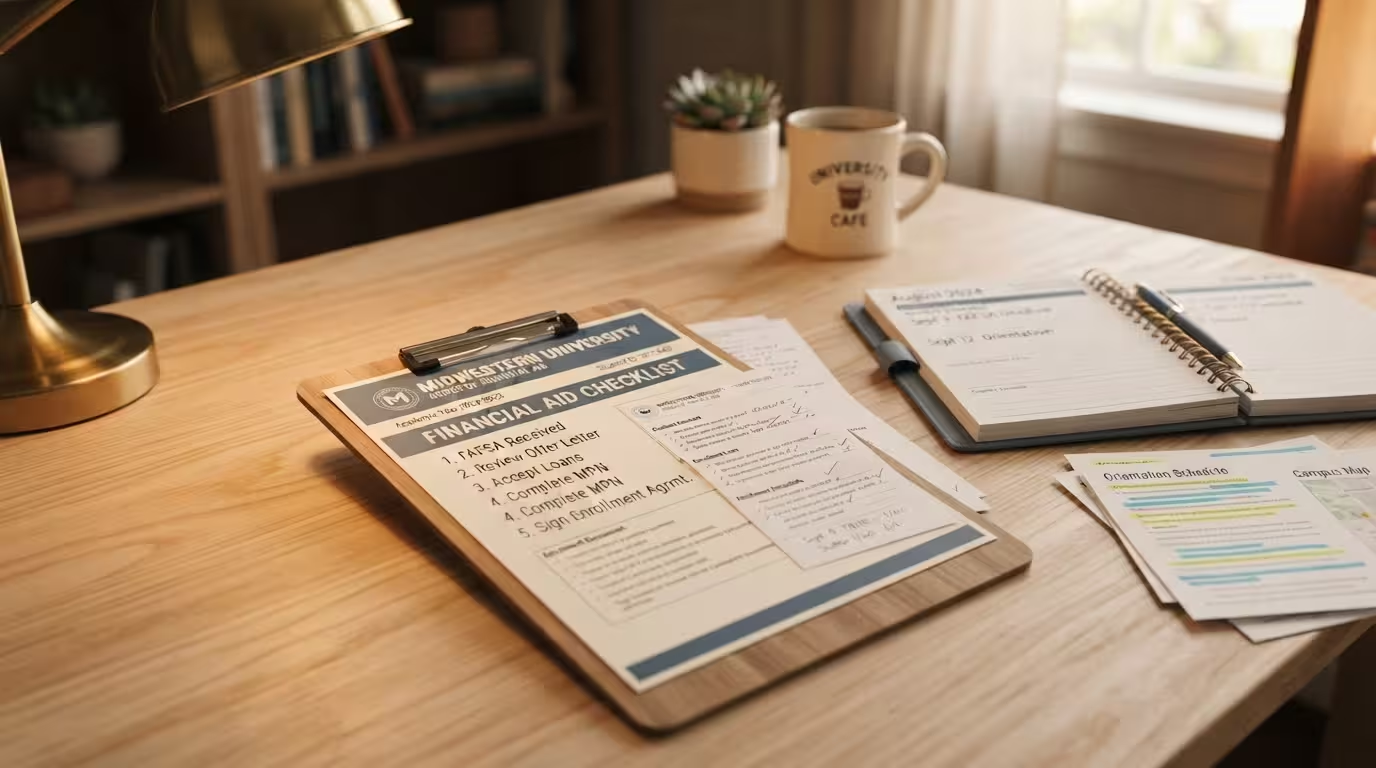
What actually determines how fast a private loan approval comes through:
- Credit profile: A strong credit score with established history moves through review faster and with fewer conditions attached
- Complete documentation: Submitting income records, enrollment proof, and school cost details upfront avoids follow-up requests that delay the process
- Cosigner: Adding a creditworthy cosigner can reduce review complexity for borrowers with limited credit history
- School certification: Even after lender approval, your school must confirm your enrollment and verify the loan amount before funds are released
From a practical standpoint, school certification is the part of the private loan process most borrowers underestimate. Funding timelines vary by lender, so ask about the full timeline from application through disbursement before you apply.
What If I Need Funding Within One Week of My Semester Starting?
If your semester begins in under a week and you do not yet have funding, a private student loan is unlikely to disburse in time. School certification adds time after lender approval, regardless of how quickly the lender decides.
In that situation, these steps give you the fastest available options:
- Contact your school’s financial aid office immediately and explain your situation. Many schools have emergency institutional loan programs that do not go through a private lender at all.
- Ask about a short-term tuition deferral. Schools will often hold your enrollment while a verified loan is in process.
- Check whether any unused federal aid from a prior award package is available to release without a new application.
- Apply for a private loan in parallel, but treat it as a backup while you pursue school-based options first.
If you are exploring private loans on your own without a cosigner, see our guide on student loans without a cosigner for lender options that do not require one.
Can You Speed Up Your Student Loan Approval?
Yes. What most people miss when comparing loan offers is that your own preparation, not just the lender’s processing speed, determines how quickly you get funded. Completing each required step promptly and submitting a complete application the first time around removes the most common sources of delay.
Decision Framework: Match Your Timeline to the Right Loan
- 6 or more weeks before your semester: Apply for federal loans through FAFSA now. This is your safest and most affordable path.
- 3 to 6 weeks before your semester: Start FAFSA immediately. Identify a private lender as a backup in case federal aid alone falls short of your costs.
- Under 3 weeks before your semester: Contact your school’s financial aid office first. Ask about emergency institutional loans. Pursue a private lender in parallel, but school certification may still delay disbursement past your tuition due date.
- Apply early. Submit your FAFSA as soon as it opens each year. For private loans, apply at least six to eight weeks before your tuition due date. Early submission reduces the risk of running into peak-period processing backlogs.
- Gather documents before you start. Have your government-issued ID, Social Security number, recent tax records, proof of enrollment, and your school’s cost of attendance information ready before opening any application.
- Complete every required step immediately after accepting a loan offer. For federal loans, that means signing your Master Promissory Note and completing entrance counseling the same day. Delays on your end directly delay disbursement.
- Consider a cosigner for private loans. If your credit history is limited, a cosigner with established credit can smooth the review process and reduce the chance of additional verification requests.
- Follow up with your school. Check your school’s financial aid portal regularly. If school certification is taking longer than expected, a direct call to the financial aid office often moves things along.
When Fast Approval Is Not Enough
If even the fastest private lender cannot disburse before your immediate need, two additional paths are worth knowing about before you give up on funding:
- Emergency institutional loans: Many colleges offer short-term emergency loans directly to enrolled students, often at zero interest with repayment due within one semester. These programs bypass private lenders entirely because no external school certification step is needed.
- School-affiliated bridge loans: Some schools maintain relationships with local credit unions or nonprofit lenders that provide small bridge loans for students caught in a verified enrollment gap. Ask your financial aid office specifically what your school offers.
For a full overview of all student loan options and repayment topics covered on this site, visit our student loans resource hub.
FAQ: Fast Approval Student Loans
Tap any question to expand the answer.
Are fast approval student loans the same as emergency student loans?
Not exactly. Fast approval student loans typically refer to private loans that can issue a lender credit decision quickly, sometimes within the same day. Emergency student loans are usually institutional programs offered directly by your college, often at zero interest and with shorter repayment terms. If you need money within a few days, your school’s emergency loan program is often the faster path because the lender certification step does not exist. Check with your school’s financial aid office to find out what emergency programs are available before applying anywhere else.
Can I get a student loan approved the same day?
Some private lenders can issue a same-day credit decision, but that does not mean funding will follow the same day. After lender approval, your school must certify the loan before disbursement can occur. This certification process adds additional time beyond what the lender controls. If you need funds available today or tomorrow for educational expenses, contact your school’s financial aid office directly about emergency institutional loans, which can sometimes disburse within 24 to 48 hours without going through an outside lender.
Does adding a cosigner make student loan approval faster?
A cosigner can improve your approval odds and may reduce the time a private lender spends reviewing your application, particularly if your own credit history is limited. A strong cosigner credit profile means fewer additional verification requests and a lower risk of denial that would force you to start over with a different lender. However, the school certification step after approval takes the same amount of time whether or not you use a cosigner. The time savings from a cosigner comes mainly from avoiding a denial and reapplication cycle, not from shortening the certification phase.
What is school certification and why does it slow down disbursement?
School certification is a required step in which the lender asks your school to confirm your enrollment status and verify that the loan amount does not exceed your cost of attendance. Your school’s financial aid office must respond to that request before the lender can release any funds. This process is required for both federal and most private student loans. Applying early in the semester cycle, when financial aid offices are less backlogged, reduces the wait compared to applying during the peak processing period from June through August.
What documents should I prepare to speed up a private student loan application?
Having the right documents ready before you apply reduces follow-up requests and keeps the review moving. Gather your government-issued ID, Social Security number, proof of enrollment or acceptance at your school, your school’s official cost of attendance figure, recent tax returns or income records, and your cosigner’s personal and financial information if you are applying with one. Submitting a complete application on the first attempt significantly reduces the chances of back-and-forth with the lender that adds days to the process.