Fast Approval Personal Loans: What to Expect and How to Qualify
By Laurel C. Yazzie | Last reviewed: October 2026
When you need money quickly, fast approval personal loans can compress what used to take weeks into a process that often wraps up within a single business day. But approval speed is not consistent across all lenders, and what one institution calls “instant approval” may not be the same as money in your bank account.
This guide explains how the approval process actually works, which lender types move the fastest, and what steps you can take today to avoid the delays that catch most borrowers off guard.
What “Fast Approval” Actually Means for a Personal Loan
The phrase “fast approval” covers two different events, and most lenders use it without making the distinction clear. The first is a pre-qualification or soft decision: an automated system reviews your basic financial profile and tells you whether you are likely to qualify. This step can happen in minutes. The second is final approval and funding: the lender verifies your income, identity, and credit history in detail before any money is released.
The time between these two steps is where most delays happen. An automated system may flag your application as approved within minutes, but your file still needs to pass through a verification queue before funds are transferred to your account.
- Pre-qualification: Soft credit check with no impact on your score; gives you estimated rates and loan amounts you may qualify for
- Formal application: Hard credit inquiry that starts the underwriting clock
- Conditional approval: Approved in principle, with final funding pending document verification
- Final approval and funding: Documents cleared; funds transferred to your bank account
The Consumer Financial Protection Bureau offers free tools to help borrowers compare personal loan offers. Reviewing the full annual percentage rate and any origination fees before accepting a loan is part of making a responsible borrowing decision, even when speed is the priority.
How Lender Type Affects Personal Loan Approval Speed
The institution you choose to apply with may matter more for approval speed than your credit score. Lenders fall into two broad underwriting categories: those that use automated systems to evaluate most applications, and those that rely on manual review by a loan officer. Automated underwriting moves faster; manual underwriting takes longer but can be more accommodating for borrowers with unusual financial situations.
In reviewing hundreds of loan applications over a decade in consumer lending, the detail most borrowers miss is that approval speed and funding speed are two separate events. You may receive an approval decision the same day you apply but wait several additional business days for funds to actually arrive, depending on the lender type and your bank’s ACH processing schedule.
| Lender Type | Underwriting Method | Relative Speed | Best For |
|---|---|---|---|
| Online lender | Automated | Fastest | Borrowers who prioritize speed above all else |
| National bank (existing customer) | Automated to semi-manual | Fast to moderate | Existing customers with verified account history |
| Credit union | Manual with member relationship | Moderate | Members willing to trade speed for lower rates |
| Community or local bank | Manual | Slower for new borrowers | Complex income or non-standard financial situations |
Funding timelines vary by lender and are not guaranteed. Before you submit a formal application anywhere, ask one question directly: “If I am approved today, when will funds reach my account?” That answer will give you a realistic picture of the timeline before you trigger a hard credit inquiry.
Which Lender Type Fits Your Timeline
The fastest lender is not automatically the right lender. Your timeline, credit profile, and loan amount should all factor into which direction you apply. A lender that moves fast but charges a significantly higher rate may cost more than a slower lender would over the life of the loan.
Decision Framework: Matching Your Timeline to the Right Lender
- If you need funds as quickly as possible: Apply with an online lender that uses automated underwriting. Ask before you apply what the cutoff time is for same-day processing, and confirm the funding timeline directly.
- If you can wait a few business days and want a better rate: Check with your current bank first. Existing customers often move through underwriting faster because the bank already has verified income and account history on file.
- If your credit score is below 670: Look for lenders that use alternative underwriting models, which evaluate employment history and cash flow alongside your credit score. This type of review may take longer, but it may be your clearest path to approval.
- If you are a credit union member: Credit unions often offer lower rates than online lenders, but their process typically runs longer. If your need is not urgent, the savings on interest over the loan term may be worth the wait.
How to Get Fast Approval Personal Loans: Step-by-Step
Your preparation has as much impact on approval speed as the lender you choose. Applications that arrive complete and accurate, with supporting documents that match the information you entered, move through underwriting faster than those with gaps or inconsistencies. The steps below apply regardless of which lender type you use.
- Check your credit report before you apply. Request your free report through AnnualCreditReport.com and review it for errors. Disputing an inaccurate account before you submit an application prevents a hold during underwriting. An error that surfaces after you have already triggered a hard inquiry can pause the process for several days while it gets resolved.
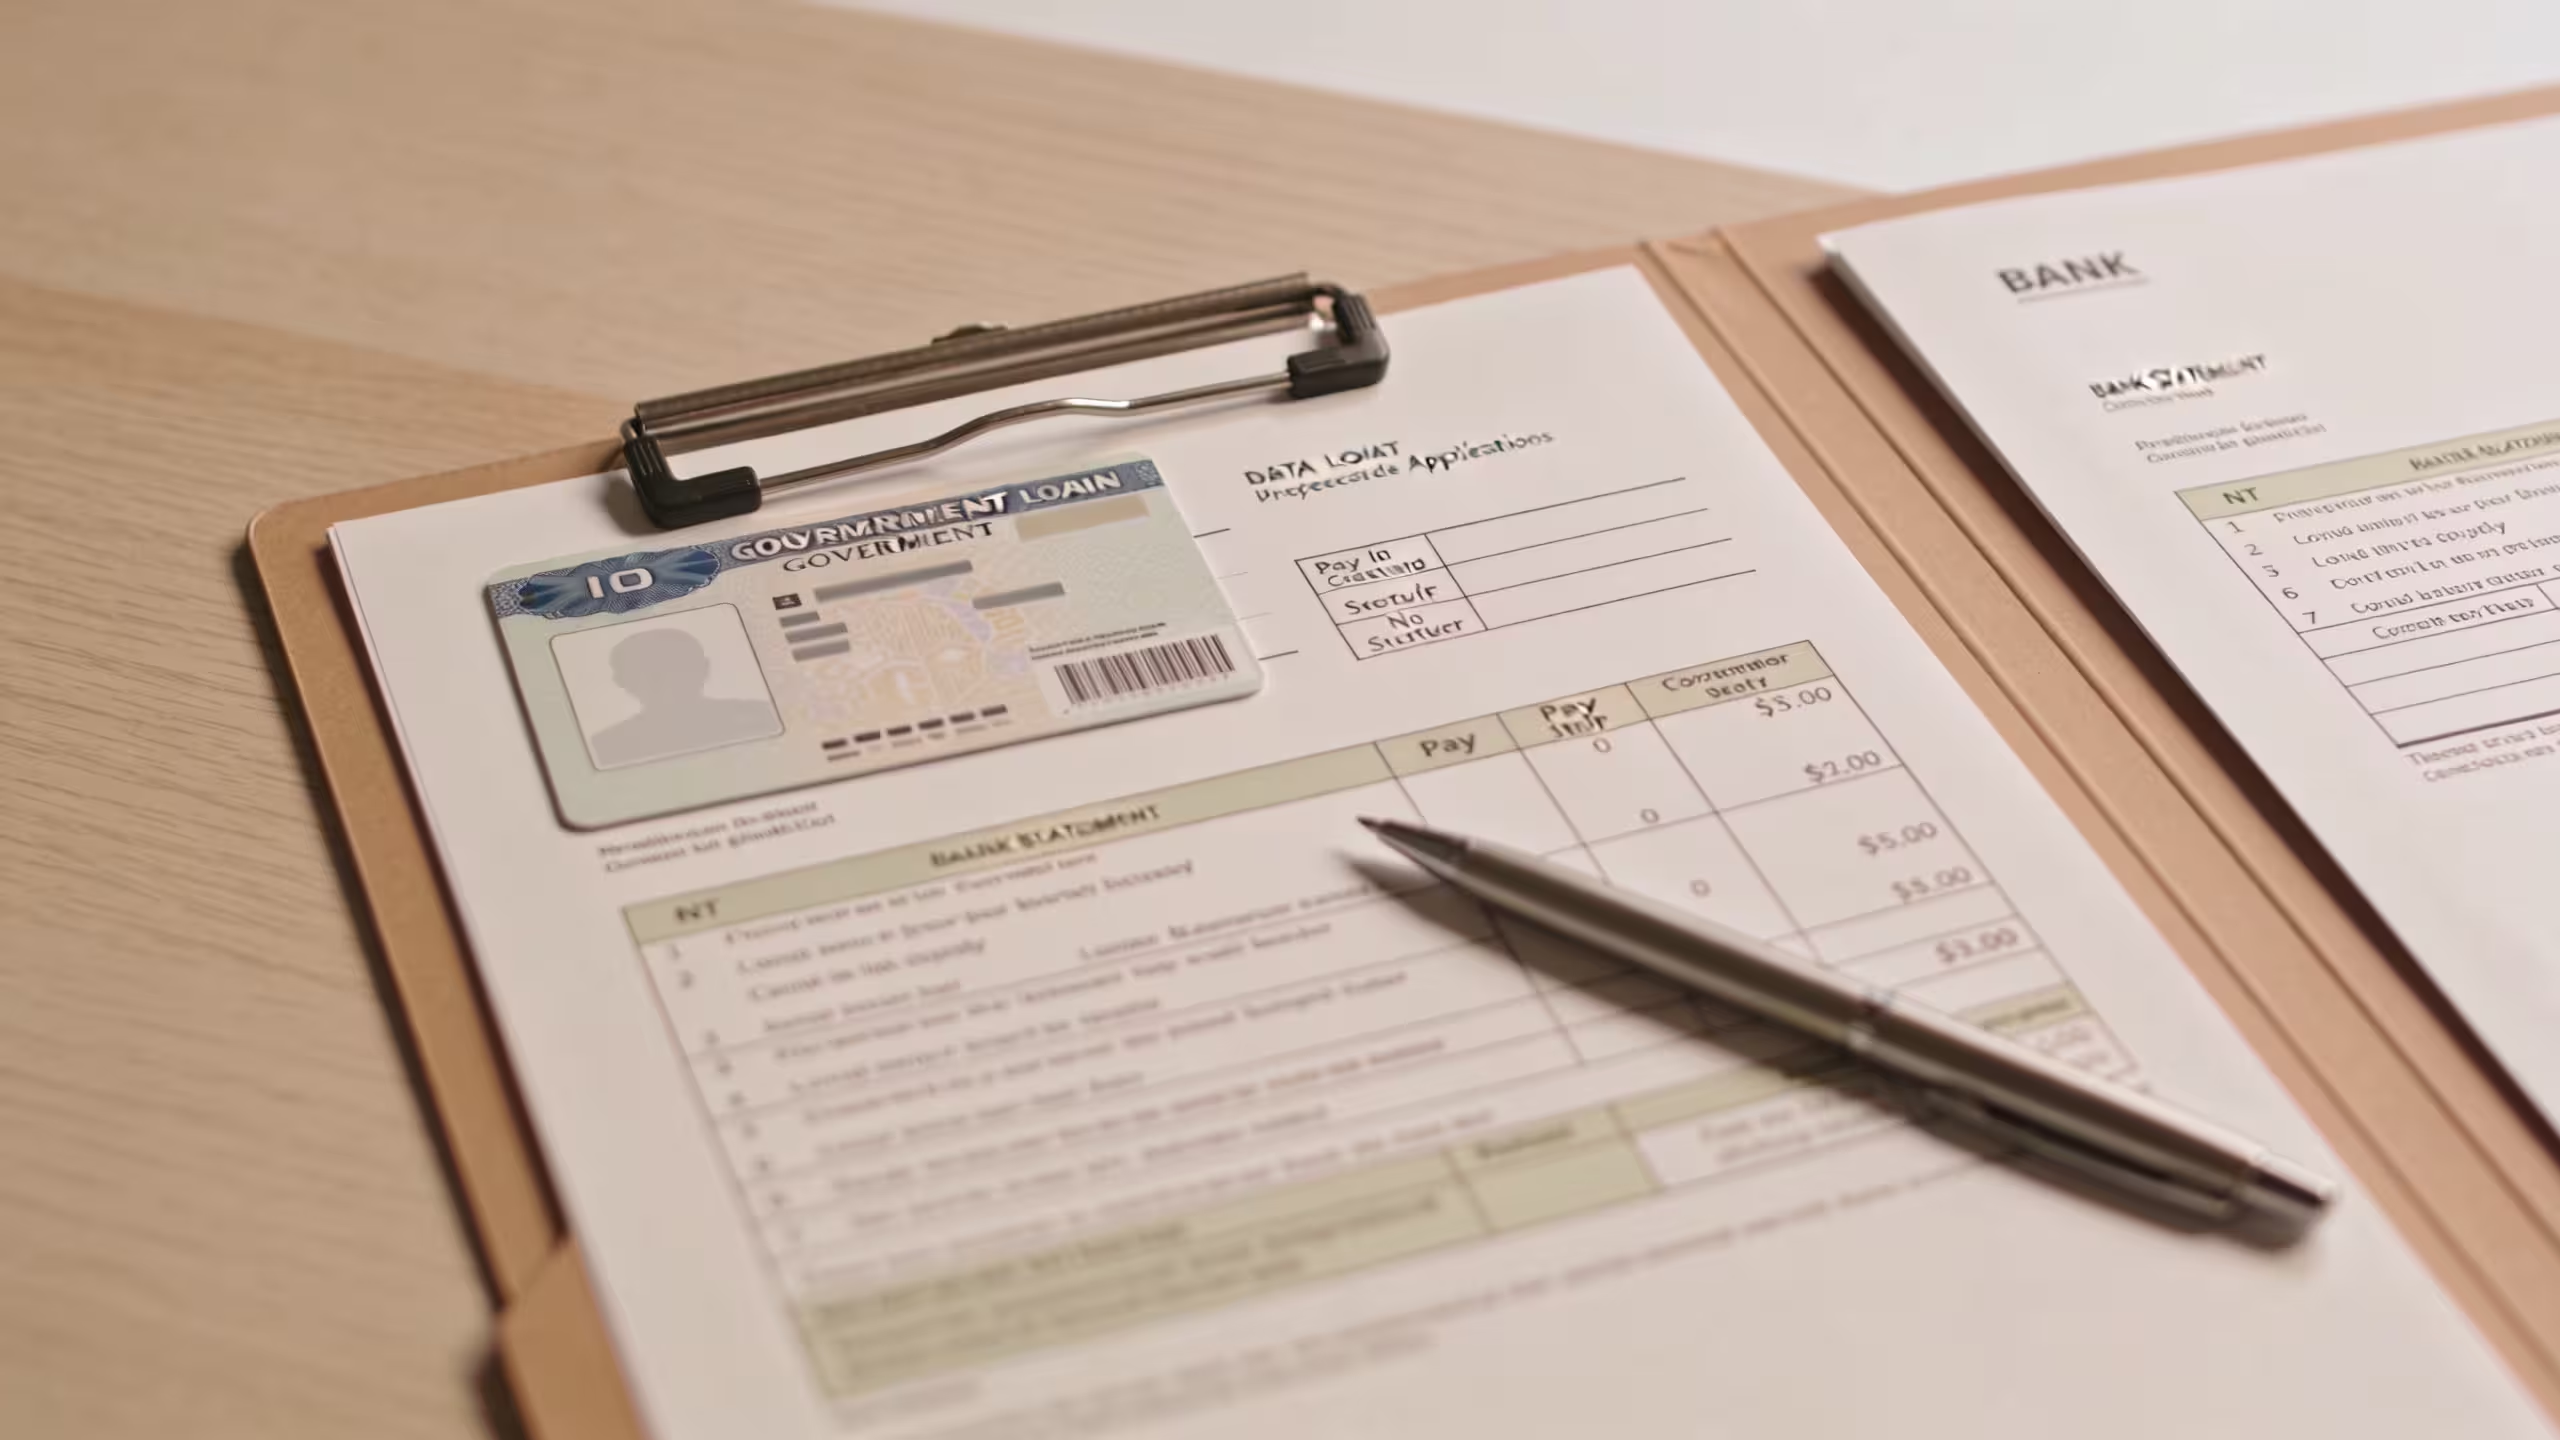
- Gather your documents before you open the application. Most lenders ask for a government-issued photo ID, your two most recent pay stubs (or most recent tax return if self-employed), proof of your current address, and your bank account and routing numbers. Having all of these ready before you start prevents the most common cause of application delays.
- Pre-qualify with two or three lenders using soft pulls. Most online lenders allow you to check your estimated rate without a hard credit inquiry. Pre-qualifying with multiple lenders lets you compare offers side by side before you decide where to apply formally, so you are not guessing which lender is best for your profile.
- Apply for a realistic loan amount. Requesting significantly more than your income can support increases the likelihood of a manual review or a counteroffer from the lender, both of which add time to the process. Keeping your request within a range that matches your documented income is the single easiest way to stay in the automated underwriting queue.
- Complete the formal application in a single session. Returning to a saved partial application may reset certain verification steps depending on the lender’s platform. Completing everything at once reduces the chance of triggering an additional review step.
- Respond immediately to any follow-up request from the lender. If a lender contacts you for additional documents or clarification, reply the same business day. Delays in responding are the most common reason an application that could have been processed in 24 hours turns into a week-long wait.
Why “Instant Approval” Can Still Lead to a Multi-Day Wait
Many lenders advertise instant or same-day approval, but this language almost always refers to an automated pre-approval decision, not a final funding commitment. The approval is conditional on verification of the documents you submitted. If the income figure you entered on the application does not match your pay stub exactly, or your address differs between your photo ID and your bank records, an underwriter may flag the file for manual review.
What most people miss when comparing loan offers is that this document-mismatch scenario is the most common cause of a “fast approval” becoming a multi-day process. Make sure every detail on your application matches your supporting documents precisely: your legal name, current address, employer name, and gross monthly income. Even a small inconsistency can shift your file from the automated queue to the manual queue, which operates on an entirely different timeline.
What to Do If Your Application Is Delayed or Denied
If your application stalls, contact the lender directly and ask for a clear status: is the delay on the document side or the underwriting side? If documents are the issue, resubmit the corrected version the same day. If you are formally denied after a pre-approval, you are entitled under federal law to an adverse action notice explaining the specific reason. Use that information to address the issue before applying elsewhere. Our overview of steps to take after a loan denial walks through your options in more detail.
If the original need was time-sensitive, such as a car repair or a medical bill that cannot wait, see our guide to personal loans for urgent expenses for alternative funding paths to explore while you address any issues with your primary application.
What Can Slow Down Your Personal Loan Application
Even when you choose a lender with fast automated underwriting, certain conditions can pause the process on your end. Most of these are within your control if you address them before you apply.
- Incomplete application fields: Blank or skipped sections send a file into a manual review queue, which moves more slowly than the automated path
- Document mismatches: Any discrepancy between what you stated and what your documents show requires a human to resolve before the file can advance
- High debt-to-income ratio: Lenders set their own DTI thresholds and rarely publish them; applying with a ratio near or above their limit may generate a counteroffer rather than a clean approval
- Loan amount outside the lender’s typical range: Requesting an amount that is unusually small or large for a given lender can trigger an extra review step or route you to a specialist queue
- Applying late on a Friday or before a federal holiday: Most lenders process ACH transfers on business days only; an approval that arrives Friday afternoon may not result in money reaching your account until Monday or Tuesday at the earliest
- Sending funds to a new bank account: Transferring to an account with no prior history at that institution may require a micro-deposit verification step that adds one to two business days
The Federal Reserve publishes average consumer credit rates on a quarterly basis. Reviewing that data before you accept any fast approval personal loan offer helps you assess whether the rate you are quoted reflects the current market or whether taking a day or two longer to compare options could save you meaningful money over the repayment term.
For a broader look at how personal loans work across different lender types, use cases, and credit situations, visit our complete personal loans guide.
Approval Speed Finder
Answer two questions to see which lender type fits your situation.
Step 1 of 2: When do you need the funds?