Out-of-Pocket Maximum: What It Is and How It Protects You
By Laurel C. Yazzie | Last reviewed: August 2026
When you shop for health insurance, your attention probably goes straight to the monthly premium. But the number that can save you thousands of dollars in a bad year is the out-of-pocket maximum. Most people only notice it when a large medical bill arrives, and by then they wish they had paid closer attention during enrollment.
Out-of-pocket maximum: An out-of-pocket maximum is the annual cap on how much you pay for covered, in-network health care services in a plan year. Once you reach this limit, your health insurance plan pays 100% of covered costs for the rest of the year. Your monthly premium and non-covered services do not count toward this cap.
Having worked directly with clients on health plan selection over a decade in the insurance industry, the most common misconception I encountered was that the out-of-pocket maximum is the same as the deductible. It is not. Confusing the two leads people to underestimate how much they could owe after a serious illness or a hospitalization.
What Is an Out-of-Pocket Maximum?
An out-of-pocket maximum, sometimes called an out-of-pocket limit, is the highest amount you will ever pay for covered health care in a single plan year. According to HealthCare.gov, once you have paid this amount through a combination of your deductible, copays, and coinsurance, your insurance covers 100% of additional covered in-network costs for the remainder of the year.
Your plan year is typically 12 months. For most marketplace and employer plans, it runs from January 1 through December 31. Everything you spend out of pocket for covered, in-network services accumulates toward the cap. On the first day of your new plan year, the counter resets to zero.
The out-of-pocket maximum exists to protect you from financial catastrophe. Without it, a serious illness, a hospital stay, or major surgery could result in unlimited personal cost. The cap means your worst-case spending scenario is knowable in advance.
- Counts toward the cap: Your annual deductible payments, copays for covered services, and coinsurance amounts
- Does NOT count toward the cap: Monthly premiums, out-of-network charges (when tracked separately), balance billing amounts, and costs for non-covered services
What Counts Toward Your Out-of-Pocket Maximum?
Understanding exactly which expenses accumulate toward your cap, and which do not, is the most practical knowledge you can take from this article. Many people assume every dollar they spend on health care counts toward the limit. That assumption is wrong and can lead to serious budget surprises during a difficult year.
Under most ACA-compliant plans, three categories of spending count toward your cap: deductible payments (what you owe before coverage begins), copays (fixed-dollar fees for covered visits and prescriptions), and coinsurance (your percentage share of costs after the deductible is met). All three accumulate together.
- Deductible payments: What you pay before your insurance starts sharing costs
- Copays: Fixed-dollar fees per visit or prescription that your plan has assigned
- Coinsurance: Your percentage share of each bill after your deductible is met
What Expenses Don’t Count Toward Your Out-of-Pocket Maximum?
This is the edge case that catches even experienced insurance holders off guard. Several common health care expenses do not count toward your out-of-pocket maximum, which means you could owe them even after you have technically hit your cap for the year.
Monthly premiums never count. You pay those to keep your coverage active, and they are separate from your cost-sharing obligations under the plan. Out-of-network charges are typically tracked against a separate out-of-network out-of-pocket limit, if your plan covers out-of-network care at all. HMO and EPO plans generally do not cover out-of-network care except in genuine emergencies, so those charges may not count toward any limit.
Balance billing is another cost to know about. If an out-of-network provider bills you the difference between their full charge and what your insurer allowed, that amount may fall entirely outside your cap. Non-covered services, including most dental and vision care on a standard medical plan and elective cosmetic procedures, are also excluded. From a practical standpoint, always verify that a provider is in-network before receiving care so that your spending actually counts toward your limit.
Understanding what coinsurance means for your bills helps clarify exactly how much you owe in the gap between your deductible and your out-of-pocket maximum.
Out-of-Pocket Maximum vs. Deductible: Key Differences
Both the deductible and the out-of-pocket maximum are annual thresholds that reset each year. The difference is what each one triggers. The deductible is the starting gate for shared coverage. The out-of-pocket maximum is the finish line for your personal spending.
Once you meet your deductible, your insurer starts sharing costs with you through copays and coinsurance. Once you meet your out-of-pocket maximum, your insurer covers 100% of covered in-network costs for the rest of the year. Your deductible payments count toward your out-of-pocket maximum, but the two amounts are not the same. Read more about how your deductible works in the full deductible guide.
| Feature | Deductible | Out-of-Pocket Maximum |
|---|---|---|
| What it is | The amount you pay before insurance starts sharing costs | The total cap on your annual cost-sharing payments |
| What happens when reached | Insurer begins sharing costs (copays and coinsurance apply) | Insurer pays 100% of covered in-network costs |
| Does it count toward the other? | Yes. Deductible payments count toward the OOP max. | N/A |
| Resets annually? | Yes | Yes |
A practical rule of thumb: if your plan’s out-of-pocket maximum is more than three times the deductible, you have a significant coinsurance zone to budget for. That middle stretch, the distance between hitting your deductible and hitting your cap, is where most people underestimate their potential annual costs. Knowing the gap in advance lets you plan with much greater accuracy.
Individual vs. Family Out-of-Pocket Maximums
If your health plan covers more than one person, you will likely have two different out-of-pocket limits to track: one individual limit and one family limit. These work together, and understanding how they interact prevents confusion when multiple household members need care in the same year.
The individual limit applies to each covered person on their own. If one member of your household reaches their individual cap, the plan covers 100% of that person’s covered costs for the rest of the year, even if the family maximum has not yet been reached. The family cap is the combined total across all covered members, after which the plan covers 100% for everyone on the plan.
- Individual out-of-pocket maximum: Applies per person. Once one member reaches it, the plan pays 100% for that person’s covered in-network care for the remainder of the year.
- Family out-of-pocket maximum: The combined total across all covered members. Once reached, the plan covers everyone at 100%.
- Embedded individual limit: Many family plans include an embedded per-person cap inside the family maximum. No single member pays more than their individual threshold before their own coverage kicks in at 100%, even if the full family limit has not been met.
- Aggregate limit: Some plans pool all family members’ spending toward one shared total with no embedded per-person cap. Under this structure, one member could in theory owe much more before the plan covers them fully.
What most people miss when reading their policy is whether the family plan uses an embedded or aggregate individual limit. Your Summary of Benefits and Coverage document must disclose which structure applies. If you cannot find it, your insurer’s member services team can confirm it before you enroll.
2026 Out-of-Pocket Maximum Limits
The federal government sets a ceiling each year on how high your out-of-pocket maximum can be under ACA-compliant plans. Plans can set lower limits than the federal maximum, but they cannot set higher ones. According to HealthCare.gov, for the 2026 plan year, the out-of-pocket limit for a Marketplace plan cannot exceed $10,600 for an individual and $21,200 for a family.
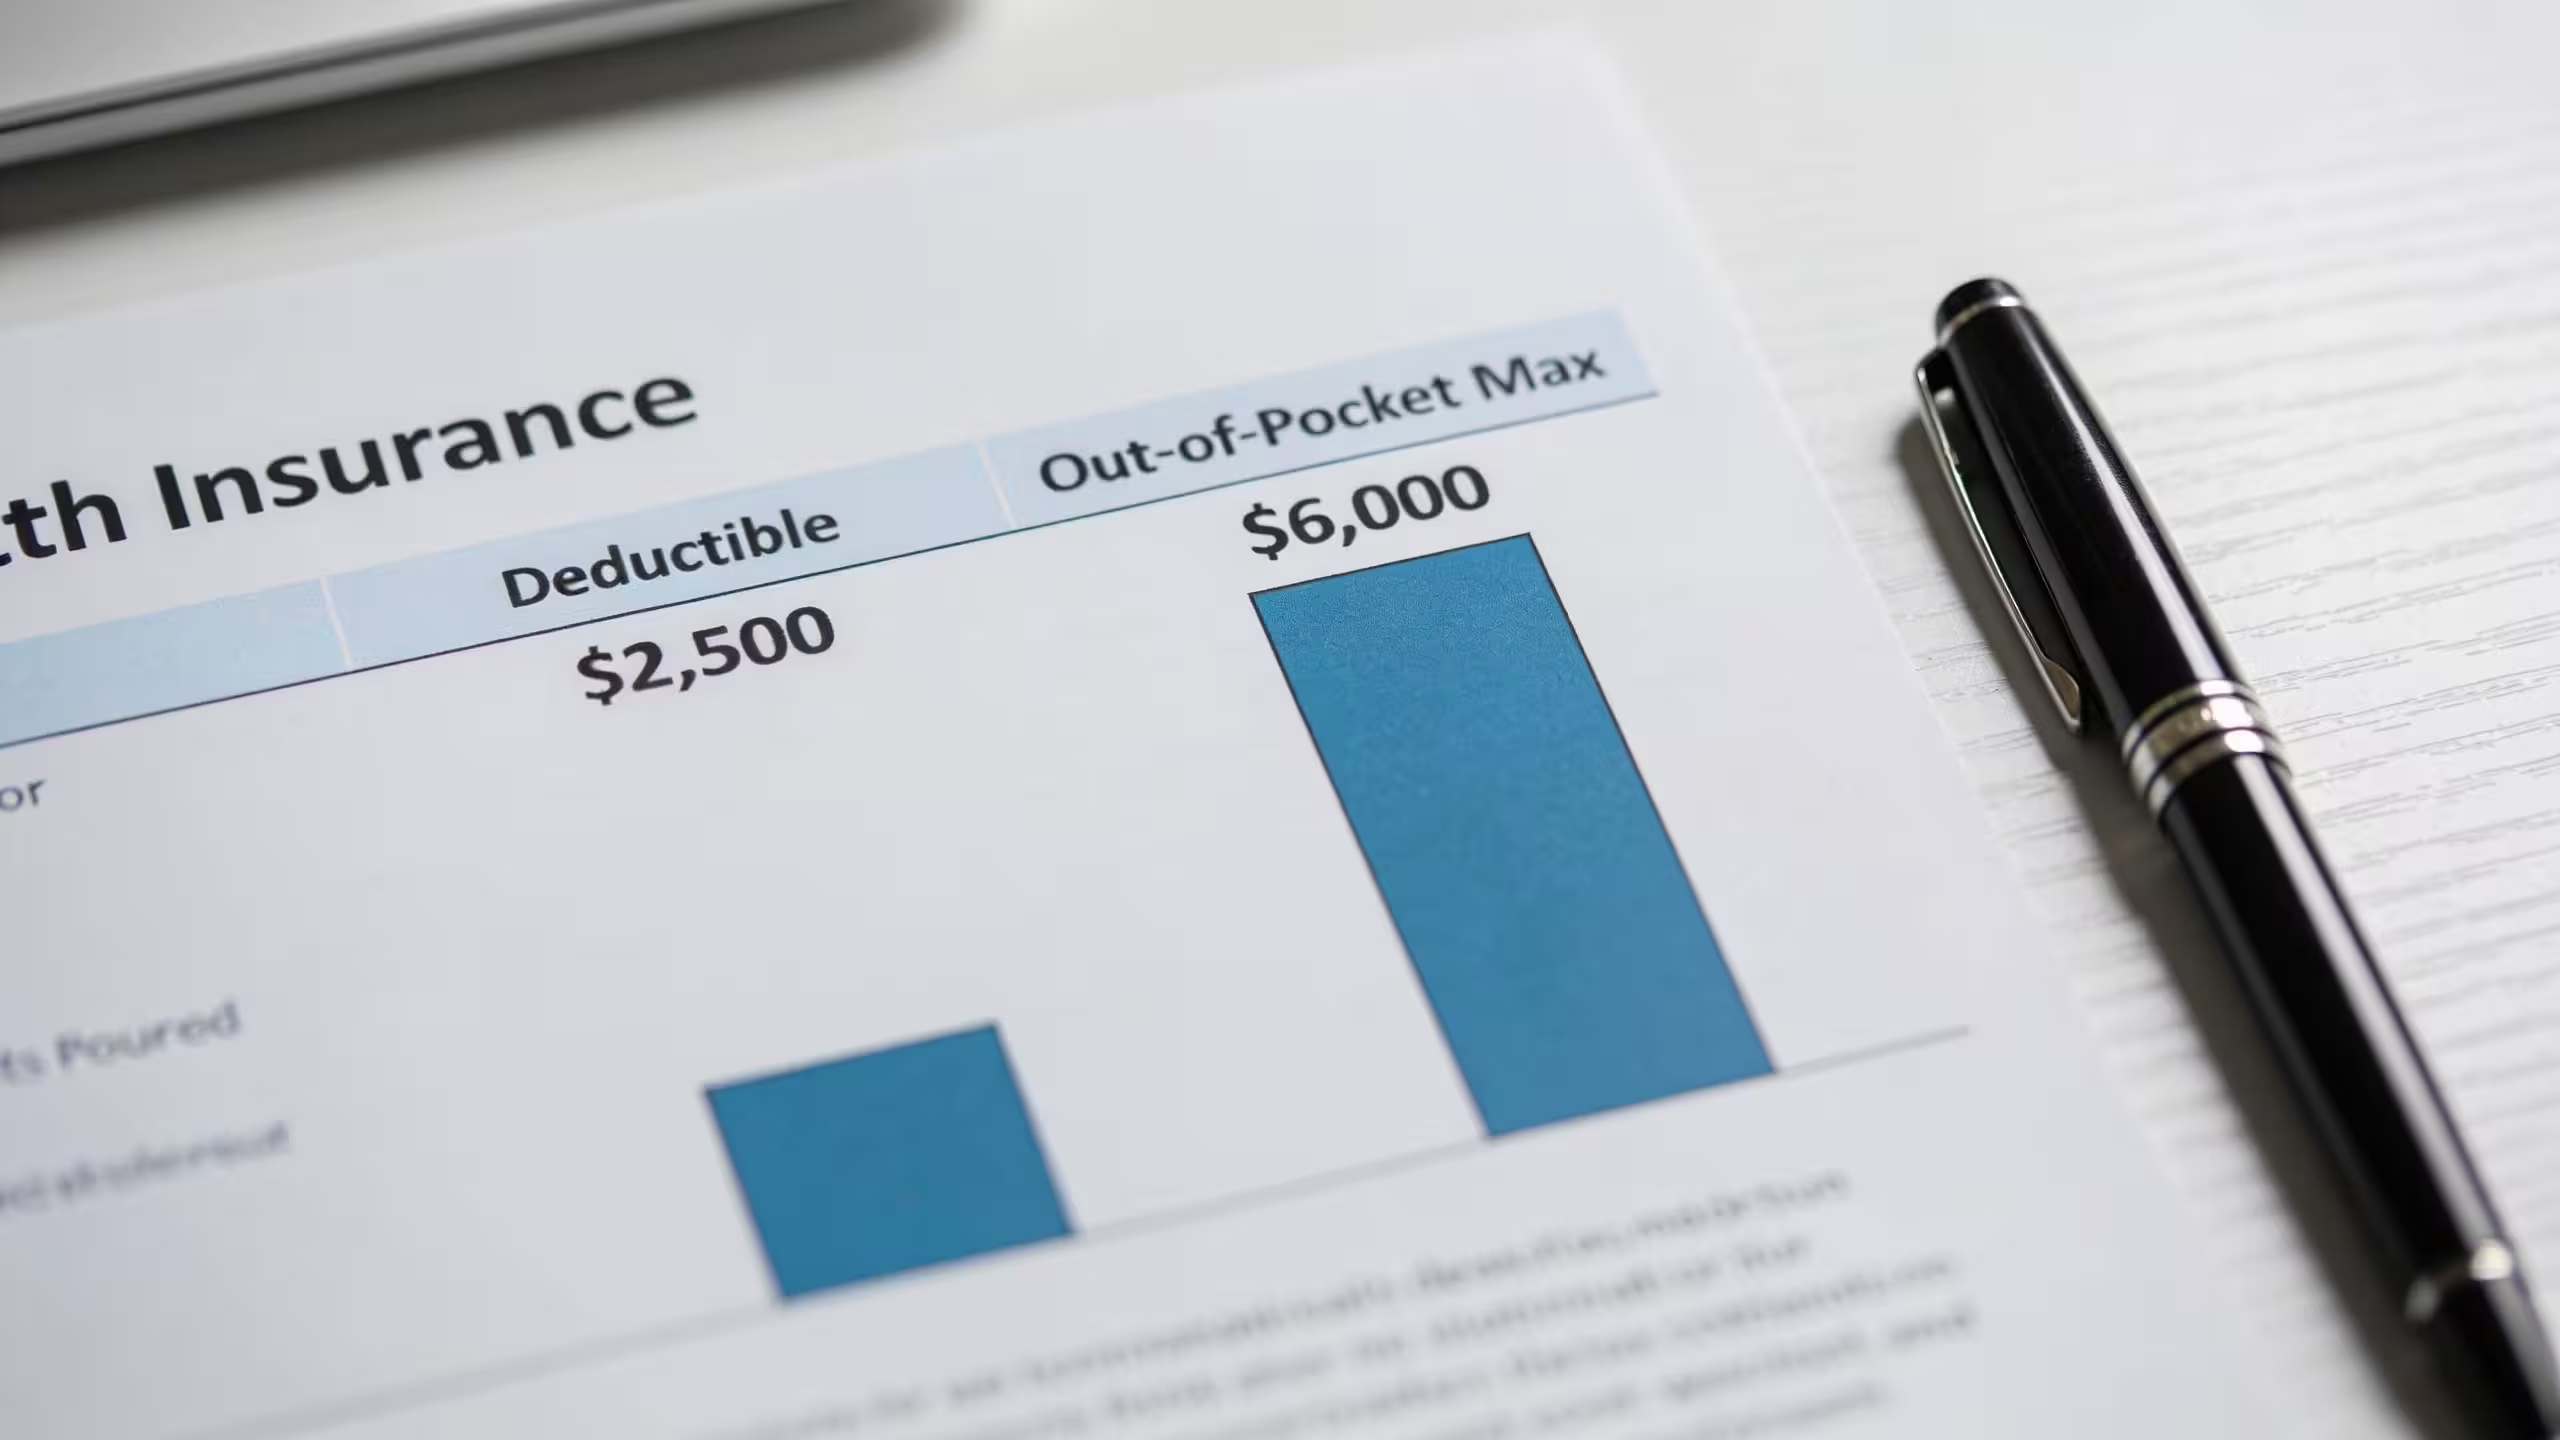
These federal ceilings apply to non-grandfathered ACA plans on and off the Marketplace, including most employer-sponsored group health plans. Many employer and higher-tier Marketplace plans set their out-of-pocket maximums well below the federal ceiling. Comparing the actual cap on each plan you are considering is one of the most valuable steps you can take during open enrollment.
- 2026 individual OOP max (ACA Marketplace): Up to $10,600
- 2026 family OOP max (ACA Marketplace): Up to $21,200
- Note: Plans may set lower limits than these federal ceilings. Always check the actual out-of-pocket maximum on your plan’s Summary of Benefits and Coverage document before enrolling.
How to Choose a Plan Based on Out-of-Pocket Maximum
Choosing a health plan based on its out-of-pocket maximum comes down to one core question: what is your realistic worst-case spending scenario? If you have a chronic condition, expect surgery, or have a family member with ongoing medical needs, a lower out-of-pocket maximum gives you more predictable financial protection, even when it comes with a higher monthly premium.
If you are generally healthy and your main concern is covering a catastrophic event, a higher out-of-pocket maximum paired with a lower premium can work well, provided you have the savings to cover that cap if a major health event occurs. The key rule is simple: never choose a plan whose out-of-pocket maximum you could not realistically pay if the worst-case scenario happened this year.
For a full overview of how all the pieces of a health plan connect, including premiums, deductibles, copays, and coinsurance, see the health insurance resource center.
The National Association of Insurance Commissioners also provides free consumer guides to help you compare plan structures and understand cost-sharing terms before you enroll.
Frequently Asked Questions: Out-of-Pocket Maximum
Tap any question to expand the answer.
What is an out-of-pocket maximum in plain language?
An out-of-pocket maximum is the most you will ever pay for covered, in-network health care in a single plan year. Once your total cost-sharing payments, including your deductible, copays, and coinsurance, reach this dollar amount, your health insurer pays 100% of covered in-network costs for the rest of that plan year. The cap resets at the start of each new plan year, so any progress you made toward it does not carry forward.
Does my monthly premium count toward my out-of-pocket maximum?
No. Monthly premiums never count toward your out-of-pocket maximum. Premiums are what you pay to keep your health insurance active, and they are completely separate from your cost-sharing obligations. Only what you pay at the point of care, such as deductible charges, copays, and coinsurance, accumulates toward the cap. This is one of the most common misunderstandings about how health insurance costs work.
What happens when I reach my out-of-pocket maximum mid-year?
Once you reach your out-of-pocket maximum, your health insurance plan pays 100% of covered, in-network health care costs for the rest of that plan year. You still owe your monthly premium, since that is not part of cost-sharing, but you will not pay any additional deductible amounts, copays, or coinsurance for covered in-network services. If you seek out-of-network care after reaching your limit, those charges may still apply, depending on how your plan handles out-of-network cost-sharing.
Does my out-of-pocket maximum reset every year?
Yes. Your out-of-pocket maximum resets at the start of each plan year. For most marketplace and employer plans, that is January 1. If your plan runs on a different calendar, such as a fiscal plan year that starts in July or October, the reset follows that schedule instead. Whatever you accumulated toward your cap during the previous plan year does not carry over. This is why it can make financial sense to schedule elective procedures before the reset date if you have already met your cap for the year.
Can my costs exceed my out-of-pocket maximum?
Yes, in certain situations. Your out-of-pocket maximum only applies to covered, in-network services. If you receive care from an out-of-network provider, those charges may count toward a separate out-of-network limit or may not count at all, depending on your plan type. Balance billing from out-of-network providers, monthly premiums, and costs for services your plan does not cover can all push your total health care spending above the stated cap. This is why staying in-network is one of the most effective ways to control your actual annual costs.