What Is Whole Life Insurance?
By Laurel C. Yazzie | Last reviewed: August 2026
Life insurance comes in two broad forms: coverage that lasts for a set number of years, and coverage that lasts your entire life. Whole life insurance belongs to the second category. It is one of the most discussed products in personal finance, and also one of the most misunderstood. Understanding the life insurance policy basics before diving into specific product types makes the comparison far clearer.
Having worked directly with clients navigating permanent life insurance decisions, the most common misconception I encountered was that a whole life policy pays beneficiaries both the death benefit and the accumulated savings account when the policyholder dies. That is not how standard policies work, and that misunderstanding leads people to either overpay for coverage they do not need or misread the value of what they have.
What is whole life insurance: Whole life insurance is a type of permanent life insurance that provides a guaranteed death benefit for your entire lifetime, as long as premiums are paid. It also builds cash value over time on a tax-deferred basis. Premiums are fixed and do not increase as you age or if your health changes.
How Whole Life Insurance Works
When you pay premiums on a whole life policy, your money is split between two purposes. Part of it covers the cost of insuring you, including policy fees and the guaranteed death benefit. Another portion accumulates in an account that grows over time on a tax-deferred basis.
According to the Insurance Information Institute, insurance companies charge premiums that exceed the actual claims cost in the policy’s early years. The company invests the surplus and draws from it later to keep your premiums level, even as the statistical cost of insuring an older person climbs considerably. This is why whole life premiums are higher than term premiums for the same coverage amount, particularly in the first decade of the policy.
- Fixed premiums: Your payment stays the same for the life of the policy, regardless of age or health changes after issue.
- Guaranteed death benefit: A set dollar amount is paid to your named beneficiaries when you die, as long as premiums have been paid.
- Tax-deferred cash value growth: A portion of each premium accumulates in a savings component that grows without current income tax.
- Permanent coverage: The policy does not expire after a set number of years. Coverage remains active as long as premiums are paid.
- Policy loans: You can borrow against your accumulated cash value without triggering immediate taxes, though unpaid loan balances reduce the death benefit.
Limited Pay Whole Life Policies
Not all whole life policies require premiums for your entire life. Some are structured as limited pay policies, where premium payments end after 10 or 20 years, or by a specified age, while coverage remains permanent. According to the National Association of Insurance Commissioners, state laws also require whole life policies to include nonforfeiture values. This means if you stop paying premiums before a policy is paid up, you are entitled to options such as reduced paid-up coverage or extended term insurance rather than simply losing the policy and all premiums paid.
The Cash Value in Whole Life Insurance: What Most People Get Wrong
In practice, many policyholders assume the cash value they have built up is a bonus pool that their beneficiaries receive on top of the death benefit when they die. That is one of the most widespread misunderstandings in life insurance, and it has real financial consequences.
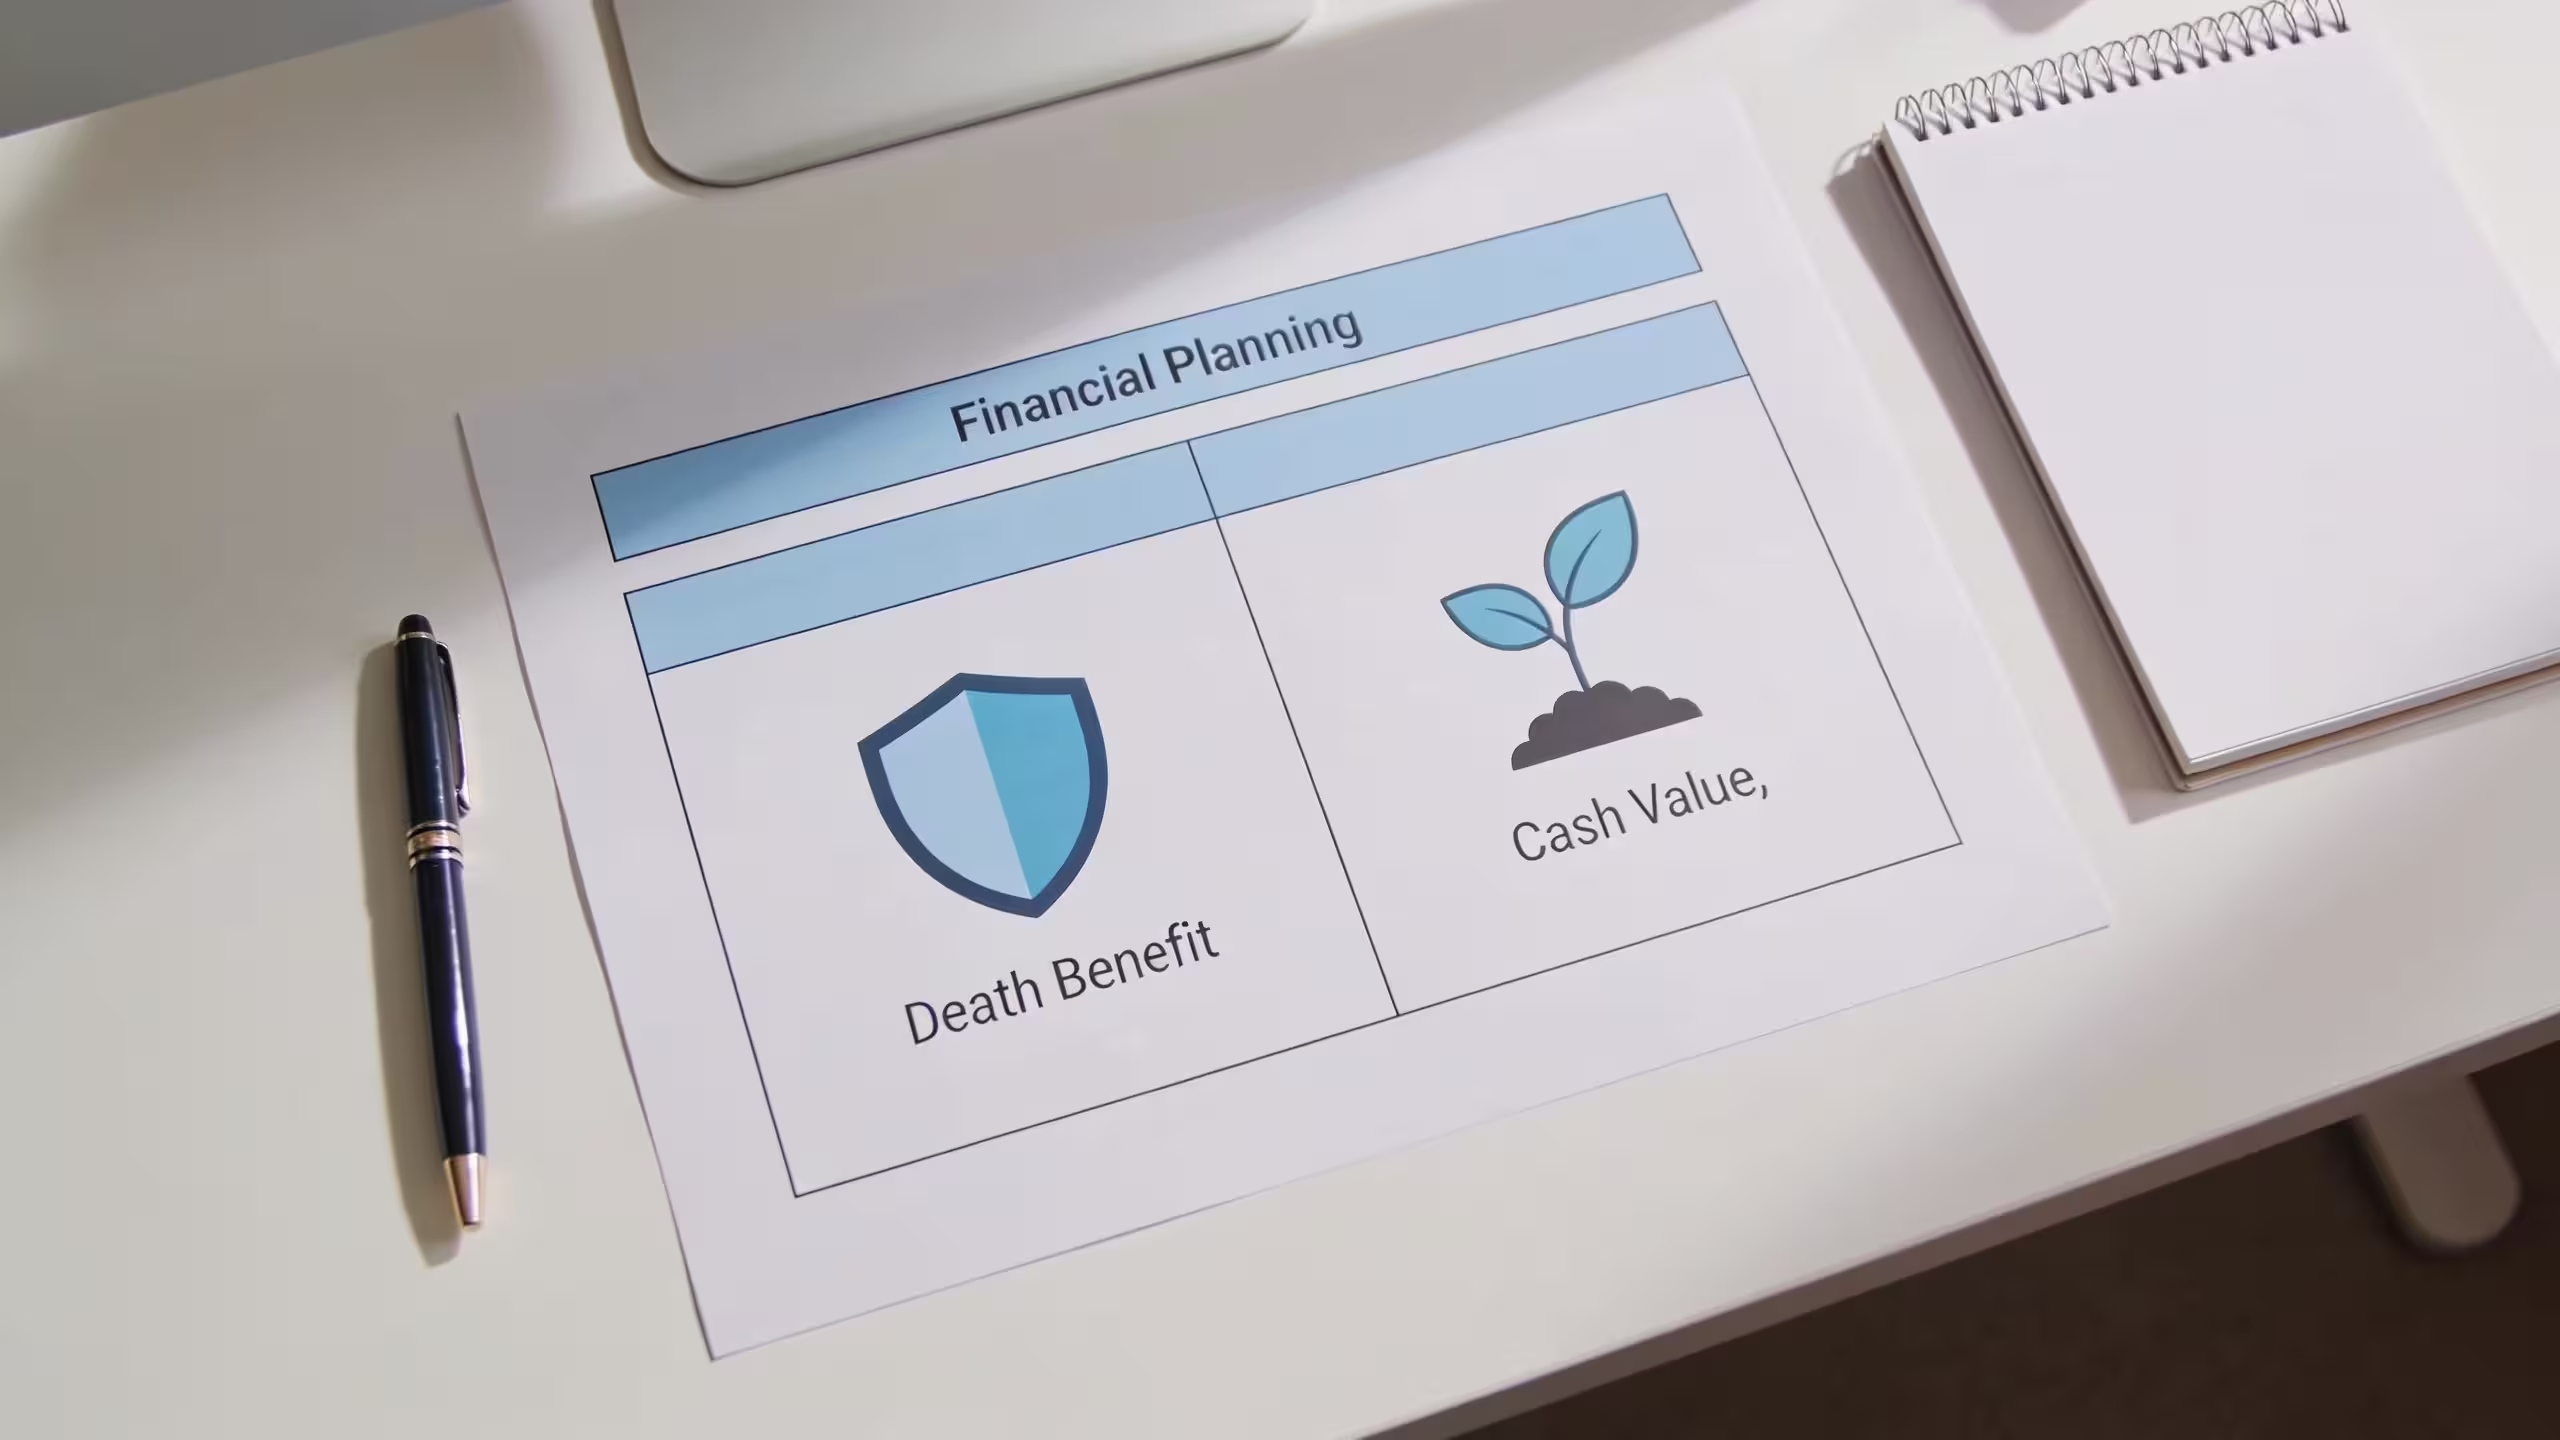
The Insurance Information Institute is direct on this point: the cash value is an alternative benefit under the policy, not an additional one. The two benefits serve different purposes:
- While you are alive: You can borrow against the cash value, withdraw from it, or use it to pay premiums if funds are tight.
- If you surrender the policy: You receive the accumulated cash value (minus any surrender charges or outstanding loan balances).
- When you die: Your beneficiaries receive the stated death benefit. The cash value is retained by the insurance company in most standard policies.
What Happens to the Cash Value When You Die?
Under a standard whole life policy, the death benefit your beneficiaries receive is the face amount written into the contract. The cash value you accumulated over decades does not pass to them separately. The Insurance Information Institute also notes that any outstanding loans you took against the cash value will reduce the death benefit paid out to your beneficiaries.
There are exceptions worth knowing. Participating whole life policies, which are issued by mutual insurance companies and pay dividends, can increase the total death benefit over time through paid-up additions. In those cases, the overall payout can grow beyond the original face amount. However, the baseline rule applies in standard non-participating policies: the cash value and the death benefit are not two separate payouts that both go to your family.
This distinction matters most when comparing whole life to a term policy combined with a separate investment account. Anyone running that comparison should account for where the cash value actually goes in each scenario.
Whole Life Insurance vs. Term Life Insurance
Understanding how term life coverage works alongside whole life makes the difference concrete. Term life covers a specific period, typically 10 to 30 years. Whole life is permanent. The right choice depends on what you need coverage to accomplish.
| Feature | Whole Life | Term Life |
|---|---|---|
| Coverage duration | Lifetime (as long as premiums paid) | Fixed term: 10, 20, or 30 years |
| Premiums | Fixed; higher than comparable term | Fixed for the term; lower than whole life |
| Cash value | Yes, grows tax-deferred over time | No |
| Death benefit certainty | Guaranteed at any age at death | Only if death occurs within the term |
| Policy expires? | No | Yes, at end of term |
| Best suited for | Lifelong coverage needs, estate planning, forced savings component | Temporary needs: mortgage coverage, income replacement while children are young |
Who Should Consider Whole Life Insurance?
Whole life insurance is not the right fit for everyone. The higher premium is the most common barrier. But for certain financial situations, the features of a whole life policy align well with long-term goals.
Use this decision framework to evaluate whether whole life fits your situation:
- You have lifelong dependents. If you support a child or sibling with a disability, or another person who will rely on your income indefinitely, term coverage creates a gap. Whole life ensures the benefit is there no matter when you die.
- You want a guaranteed inheritance. Whole life provides certainty that a term policy cannot. If leaving a specific dollar amount to heirs regardless of timing matters to you, whole life delivers that reliably.
- You are in a high estate-value situation. Whole life is commonly used in estate planning to provide liquidity for estate tax obligations so heirs are not forced to sell assets.
- Your primary need is income replacement during working years. In that case, term life typically delivers a larger death benefit at significantly lower cost, and may be the better-suited tool.
- You have already maxed out other tax-advantaged accounts. If your 401(k) and Roth IRA are fully funded, the tax-deferred cash value growth in whole life can play a supporting role in a broader financial strategy.
What most people miss when reviewing their policy options is that whole life and term are not always an either/or choice. Some people hold both: a term policy for income replacement during the high-expense years, and a smaller whole life policy for permanent needs such as final expenses or estate planning. Choosing beneficiaries carefully for each policy matters in this structure. Related topics worth reviewing include how factors such as age and health affect your rates, and how to life insurance guides and resources can help you compare options across coverage types.
FAQ: Whole Life Insurance
Tap any question to expand the answer.
What is whole life insurance in simple terms?
Whole life insurance is a type of permanent life insurance that covers you for your entire lifetime, as long as you pay your premiums. Unlike term life insurance, it never expires after a set number of years. It also includes a cash value component that grows over time and can be accessed while you are still alive, either through withdrawals or policy loans.
Can I borrow money from my whole life insurance policy?
Yes. Once your whole life policy has accumulated sufficient cash value, you can take out a policy loan against it. These loans do not require a credit check and do not trigger immediate income taxes. However, any outstanding loan balance, including interest, will reduce the death benefit your beneficiaries receive if the loan is not repaid before you die.
What happens to the cash value when the insured person dies?
In a standard whole life policy, the beneficiaries receive the stated death benefit and the insurance company retains the accumulated cash value. The cash value is a living benefit designed for the policyholder to use during their lifetime, not an additional payout at death. Some participating policies issued by mutual companies work differently, as dividends applied as paid-up additions can increase the total death benefit over time, but this is a feature of those specific policy types and not the default.
Is whole life insurance worth the higher cost?
Whether whole life is worth it depends on what you need coverage to accomplish. For people with lifelong dependents, estate planning needs, or a desire for permanent guaranteed coverage, the higher premium may align with those goals. For people who need the largest possible death benefit during their working years at the lowest cost, term life typically delivers more coverage per dollar. The NAIC provides a consumer guidance resource on life insurance types at content.naic.org.
What are nonforfeiture values in a whole life policy?
Nonforfeiture values are consumer protections that state law requires whole life policies to include. If you stop paying premiums before the policy is fully paid up, you do not automatically lose all the value you have built. Common nonforfeiture options include reduced paid-up insurance, which provides a smaller permanent death benefit with no further premiums required, and extended term insurance, which converts the cash value into a term policy with the original death benefit for a set number of years. These options give policyholders flexibility if their financial circumstances change.